AI demand is accelerating datacentre investment across Europe, but access to power, the rising cost of development, and the opposition against it are changing what gets built and how quickly capital can be deployed.
TMT Finance Europe brings together the senior dealmakers behind the market’s largest projects and transactions to examine how the investment case is evolving as the sector scales.
2 days of dealmaking insights across datacentres and the digital infra ecosystem.
12:20
-
- Is a Neocloud fundamentally a GPU capacity trade, or a durable infrastructure platform? and where does the real economic moat sit: the platform itself, access to power, or something else once GPU scarcity eases?
- Are Neoclouds ultimately enabling Hyperscalers to build faster, or creating businesses that could eventually compete with them?
- Does the size and flexibility of the balance sheet ultimately determine who can scale and compete in compute?
- How much customer concentration can investors accept, and is there an investable case for a Neocloud without a hyperscale tenant?
- With concerns emerging around Neocloud tenancy in recent transactions, are European investors more cautious than their US counterparts? And what can operators do to get investors comfortable with the risk?
15:30
-
- What is bringing assets to market? Sponsor exits, portfolio rationalisations, growth capital requirements or a wider strategy shift?
- Are buyers paying for existing cashflow, connectivity and market positions, or underwriting future expansion and potential to capture some AI demand?
- Which characteristics are the strongest determinators of high valuations?
- Why are some processes proving difficult to execute?
- Will the current pipeline create new, scaled regional champions?
16:50
-
- How do the investment cases differ across AI training campuses, metro-connected AI and colo, sovereign infrastructure and regional platforms?
- What distinguishes a complete location thesis from a power-led development proposition?
- What happens when the first large training customer leaves? And can assets be re-let and refinanced without the original tenant?
- How are lenders accounting for tenant concentration and residual value differently in tier 2 and 3 markets?
- Is there sufficient lender appetite to clear the required development funding?
- Which projects can progress from development and high-yield capital into lower-cost permanent ownership?
- How do the opportunities and execution risks vary across Norway, Finland, Denmark and Sweden?
10:40
-
As Europe’s datacentre development pipeline becomes increasingly capital intensive, more than E1bn of YieldCo and StableCo processes are under way – according to TMT Finance data – enabling operators to monetise mature assets and recycle capital into new capacity. These structures are also creating new entry points for pension funds, insurers and core infrastructure investors seeking stable, long-term contracted cashflows. Indicative cap rates of 5.5-6% point to strong demand and a growing market for stabilised assets, but also raise questions around whether pricing adequately reflects tenant concentration, power certainty, future capex and re-leasing risk. This panel will explore:
- What genuinely qualifies a datacentre for StableCo or YieldCo ownership?
- What cap rates/equity yields would make the transactions accretive to both the developer and the investor?
- Can datacentres consistently deliver the long-duration, predictable cash flows required?
- How will ABS and other securitisations support capital recycling and the transition to permanent ownership?
- Can capital recycling release enough equity to sustain Europe’s development pipeline?
Moderator
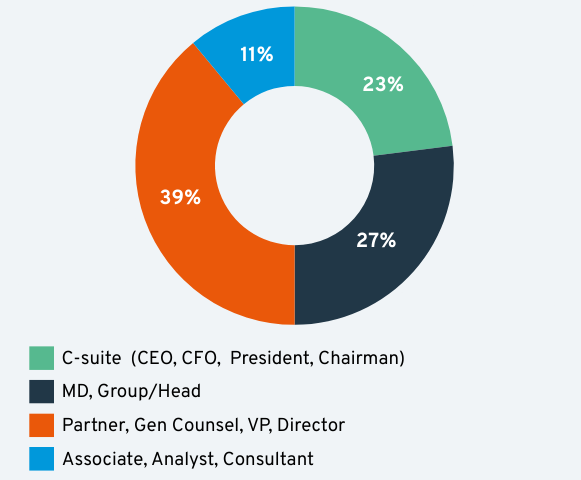
89% of attendees are C-suite, MD, Head of Dept, or Partner level
A live deal ecosystem,A live deal ecosystem
“I thoroughly enjoyed the event... I was impressed by the strong lineup—a great mix of industry executives, bankers, and investors. The topics covered were highly relevant, addressing the key areas shaping the industry”
"A really good event with many operators and investors participating"
"The networking is amazing"
"Definitely a must attend for us, we come here every year. It's an excellent opportunity for us to meet a wide range of clients and peers, and to discuss the latest sector trends and developments"
"Great content to hear the latest trends around M&A and Financing. Fantastic networking opportunities"
"A lot of deals get done because of the connections you make at events like this"